Executive Strategic Perspective
Islamic banking represents over $3.2 trillion in global financial assets, with the Gulf Cooperation Council (GCC) serving as its primary engine. Yet, for too long, digital applications in Islamic banking have been treated as mere adaptations of conventional banking software—often slapping Arabic translations and generic terms onto interest-based architectures.Today's Islamic banking customers—particularly younger, digitally-native GCC citizens—demand more than surface-level labeling. They expect complete transparency regarding underlying assets, clear contractual sequencing that conforms strictly to Islamic jurisprudence, and digital experiences that rival the most sophisticated neobanks.
Fintechify builds native, Sharia-first digital banking architectures. We bridge the gap between complex Fiqh al-Muamalat principles and modern software engineering, translating AAOIFI standards and Sharia board rulings into deterministic code, intuitive visual journeys, and automated audit trails.
Digitized Islamic Contract Architectures
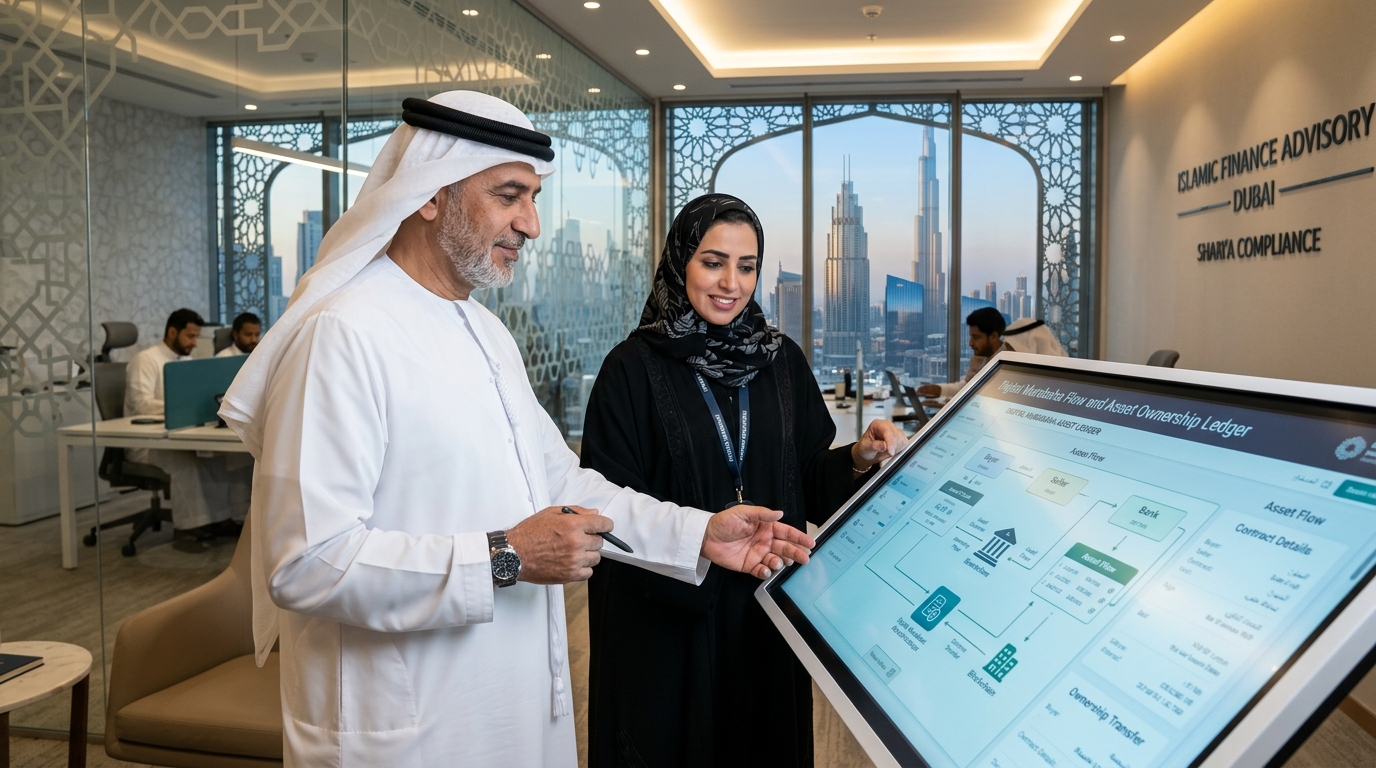
01 / Digital Commodity Murabaha (Personal & Auto Financing)
- Sequential Contract State Machine: Enforcing the strict chronological sequence required by Sharia—ensuring the bank purchases and acquires title to the underlying commodity (via local or international brokers such as DMCC or Bursa Suq Al-Sila) before the resale contract is executed with the customer.
- Transparent Cost & Profit Visualization: Clear, unbundled display of asset purchase cost, bank profit margin, and fixed repayment schedules without hidden compounding calculations.
- Digital Offer & Acceptance (Qabul & Ijab): Legally binding, cryptographically signed digital acceptance executed seamlessly within the mobile application.
02 / Digital Ijara (Asset Leasing & Ownership Transfer)
- Real-Time Asset Lifecycle Tracking: Visual interfaces showing underlying property or vehicle ownership status, insurance allocations (Takaful), and rental payment distributions.
- Promised Transfer of Ownership (Ijara Muntahia Bittamleek): Automated generation and digital execution of final transfer deeds upon completion of lease payments.
03 / Mudaraba & Wakala Savings & Investment Pots
- Dynamic Profit-Sharing Calculators: Transparent visual calculators that display historical and projected indicative profit-sharing ratios (PSR) rather than deceptive fixed interest rates.
- Goal-Based Sub-Accounts: Enabling users to segregate savings into purpose-driven digital pots with automated Wakala fee disclosures.
04 / Automated Zakat & Charitable Giving Engines
- Central Bank & Sharia-Aligned Zakat Calculations: Automated balance assessment applying lunar or solar calendar standards to calculate exact Zakat due across qualifying liquid assets.
- Direct Waqf & Charity Rails: One-tap round-up donations integrated directly into mobile debit card spending, disbursing funds directly to licensed regional charitable foundations.
The Sharia Governance & Audit Architecture
+-------------------------------------------------------------------------+
Customer-Facing Digital Journey Intuitive Murabaha Steps Visual Contract Summary
+-------------------------------------------------------------------------+
v
+-------------------------------------------------------------------------+
Deterministic Sharia State Machine [ Step 1: Customer Financing Request ] [ Step 2: Automated Bank Commodity Purchase & Title Confirmation ] [ Step 3: Formal Murabaha Resale Offer to Customer ] [ Step 4: Digital Acceptance & Cryptographic Signature ] [ Step 5: Instant Liquidation & Immediate Account Credit ]
+-------------------------------------------------------------------------+
v
+-------------------------------------------------------------------------+
Immutable Sharia Supervisory Audit Ledger Time-stamped commodity certificates, digital signatures, and audit records ready for Sharia Board and Central Bank review
+-------------------------------------------------------------------------+
Regulatory & Industry Standards Alignment
- AAOIFI Standards: Full compliance with Accounting and Auditing Organization for Islamic Financial Institutions governance and Sharia standards (specifically Sharia Standard No. 8 on Murabaha and No. 9 on Ijara).
- Central Bank Regulatory Alignment: Conforming to CBUAE Higher Sharia Authority regulations and SAMA Islamic Banking Directives.
- Islamic FinTech Architecture: Microservice adapters connecting directly to Sharia-compliant core platforms (such as Temenos Islamic, Ethix, and iMAL).
Related Case Studies & Proven Work
Sharjah Islamic Bank (SIB)
Comprehensive digital platform review and benchmarking across four flagship mobile applications, uncovering friction points and delivering an actionable modernization roadmap.
Explore Engagement
Al Rajhi Bank Malaysia · Rize Digital Bank
Next-generation digital bank platform delivering 15-minute personal financing, Ready CashLine credit, digital term deposits, and 99.98% crash-free stability.
Explore Engagement
GCC NeoBank UX Benchmark Report
Comprehensive usability audit evaluating a 34-step onboarding journey, 13 maturity dimensions, wealth marketplace, and conversational AI.
Explore Engagement